
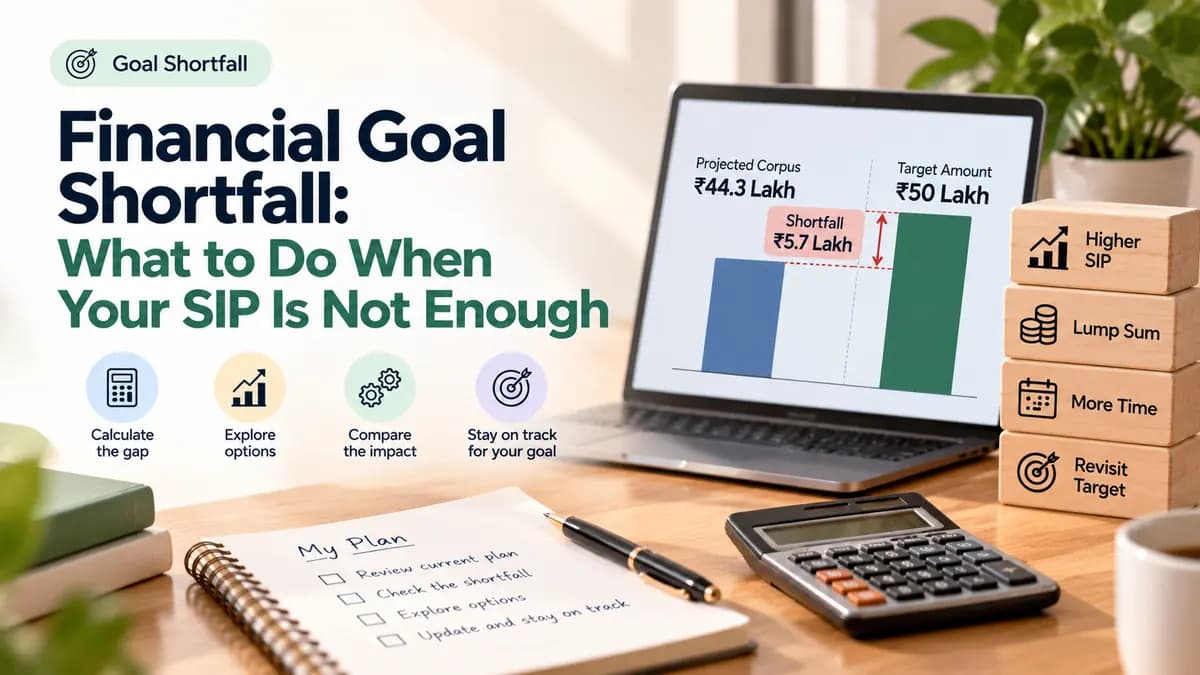
Financial Goal Shortfall: What to Do When Your SIP Is Not Enough
If your current investments and planned SIP are projected to leave you below your target, the next step is to measure the shortfall and understand what can realistically change without losing sight of the goal.
01 Oct 2026 • 9 min read • Shweta Kataria (Content & Digital Marketing)
What should you do if your financial goal is projected to fall short?
If your existing investments and future SIP are projected to build less money than you need by the goal date, you have a financial goal shortfall.
The next step is to calculate the size of that gap and compare the parts of the plan that can realistically change. Depending on the goal, this may mean increasing the monthly investment, stepping it up gradually, adding a lump sum, allowing more time or revisiting the target amount.
The comparison should be made using the same target, timeline and return assumptions so that you can see what each adjustment actually changes.
If you have not yet calculated how much your goal requires each month, start with Goal-Based SIP: How Much Should You Invest Monthly to Achieve Your Financial Goal?
This guide starts one step later, when the goal and current investment plan already exist but the projected corpus is not enough.
What is a financial goal shortfall?
A financial goal shortfall is the difference between the amount required on the goal date and the amount your current plan is projected to accumulate by then.
It is not simply the target amount minus what you have invested today. Money already invested may continue to grow, and you may make many more contributions before the goal becomes due.
A useful way to express it is:
Financial goal shortfall = Target amount − Projected corpus on the goal date
Suppose you need ₹50 lakh in ten years. After accounting for the money already invested and all the SIPs you plan to make during those ten years, your projected corpus is ₹44.3 lakh.
Your projected shortfall is therefore approximately ₹5.7 lakh.
If you do not yet know whether your goal is actually ahead or behind its required path, How Do I Know If I’m On Track to Achieve My Financial Goal? explains that assessment separately.
A ₹50 lakh goal that is projected to fall short
Consider a financial goal with a target of ₹50 lakh and ten years remaining.
Suppose ₹5 lakh is already invested towards the goal and you are contributing ₹15,000 a month. Using an illustrative annual return assumption of 10%, with contributions assumed at the end of each month, the existing corpus and future SIPs would be projected to grow to roughly ₹44.3 lakh.
The plan is therefore approximately ₹5.7 lakh short of the target.
The useful question is no longer whether the plan has a gap. You already know that it does. The question becomes what adjustment could close it.
Approach | Change to the plan | Approximate projected outcome |
Current plan | ₹5 lakh invested + ₹15,000/month | ₹44.3 lakh |
Higher monthly SIP | Increase SIP to about ₹17,800 | Around ₹50 lakh |
Additional investment today | Add about ₹2.1 lakh and continue ₹15,000/month | Around ₹50 lakh |
More time | Continue the current plan for about one additional year | Around ₹50.8 lakh |
These numbers are illustrations rather than expected investment outcomes. Actual returns can differ from the assumption used, so a goal should continue to be reviewed as its target, contributions and investment value change.
Can increasing the SIP close the funding gap?
If your monthly cash flow allows it, increasing the SIP is one of the most direct ways to address a shortfall without changing either the target or the goal date.
In the example above, the current monthly investment is ₹15,000. Under the same assumptions, a monthly investment of approximately ₹17,800 would be required to bring the projected value close to ₹50 lakh over ten years.
The relevant adjustment is therefore approximately ₹2,800 a month.
Looking at the gap this way can be more practical than focusing only on the ₹5.7 lakh future shortfall. When several years remain, a relatively smaller change in the monthly contribution has more time to accumulate towards the target.
The exact SIP required will vary with the amount already invested, the remaining timeline and the assumptions used. For the full process of calculating the monthly contribution for a newly defined goal, refer to Goal-Based SIP: How Much Should You Invest Monthly to Achieve Your Financial Goal?
What if you cannot increase the SIP immediately?
A higher flat SIP may close the mathematical gap, but it may not fit comfortably within your current budget.
In that situation, a planned step-up can be considered. Instead of moving immediately from the existing contribution to the full required amount, the SIP can increase gradually as income and available surplus change.
The step-up should come from the actual funding requirement rather than an arbitrary percentage. A goal that is slightly behind with fifteen years remaining may need a very different increase from a goal with a larger shortfall and only five years left.
The calculation also needs to be revisited if the planned increases do not happen. A step-up helps only when the future contributions assumed in the plan are actually made.
Can a lump sum help close a financial goal shortfall?
An additional investment made earlier can reduce the amount that needs to come from future monthly contributions.
Returning to the ₹50 lakh example, investing approximately ₹2.1 lakh additionally today and continuing the ₹15,000 monthly SIP would bring the projected value close to the target under the same illustrative assumptions.
The additional amount required today is smaller than the ₹5.7 lakh projected future shortfall because the money has ten years to potentially grow.
A bonus, accumulated surplus or another available amount can therefore be assessed as part of the goal rather than treated separately. The effect should still be recalculated using the same timeline and assumptions instead of assuming that any lump sum will automatically solve the gap.
Can extending the goal timeline help?
More time can materially change a funding calculation, but extending the deadline is appropriate only when the goal itself is flexible.
In the same example, keeping the ₹5 lakh existing investment and ₹15,000 monthly SIP for roughly one additional year would take the projected corpus to around ₹50.8 lakh under the same assumptions.
A home purchase, holiday or other discretionary goal may allow such a change. A child's college admission date may offer much less flexibility.
The deadline should therefore reflect when the money will genuinely be needed. Moving the date simply because it improves the calculation does not solve the underlying problem if the expense cannot actually be postponed.
Should you reduce the target amount?
A target can be revisited when the expected cost or scope of the goal is genuinely flexible.
If a discretionary goal was originally estimated at ₹50 lakh but can still meet its purpose at ₹45 lakh, revising the target may be reasonable. The same approach may not work for a goal where the cost is largely outside your control.
The decision should begin with the real-world goal rather than the investment calculation. Reducing the target is useful only when the underlying expense can also be changed.
Do not make the shortfall disappear by assuming a higher return
A funding gap can appear smaller if the expected return entered into the calculation is increased.
The amount actually being invested has not changed.
A plan that falls short using an illustrative 10% return may appear fully funded if the assumption is raised to 12% or 14%, but the portfolio would then have to earn that higher return for the projection to materialise.
Return assumptions are necessary when estimating a future corpus, but they should not be adjusted merely to make an underfunded goal appear funded.
It is more useful to compare the parts of the plan you can directly influence, including contributions, additional investments, the target and, where possible, the timeline.
What if several financial goals are short at the same time?
A different problem arises when your available monthly investment has to support several goals and the combined amount required is more than you can currently invest.
Suppose all your goals together require ₹75,000 a month while your available investment budget is ₹50,000. The issue is no longer only how to repair one goal. You also need to decide how the available ₹50,000 should be allocated between goals with different amounts, deadlines and levels of flexibility.
That question is covered in I Have Multiple Financial Goals: How Should I Split My Monthly Investments?
Keeping the two decisions separate prevents this page from becoming a general goal-prioritisation guide. Here, the focus remains on what can be changed once an individual goal has already been identified as underfunded.
What if the shortfall is for your child's education?
The same shortfall framework can be used for a child's education goal, but the room available to change each variable may be different.
A parent may be able to increase contributions or add a lump sum, while moving the college date may not be realistic. The expected cost of education can also change significantly over a long planning period, which means the target itself may need to be updated before deciding how large the shortfall really is.
For the broader process of estimating and funding education expenses, see Child Education Planning in India: A Complete Beginner Guide for Parents.
Once the education target and timeline are established, this shortfall framework can be used when the projected investments are no longer sufficient to meet that amount.
What if the goal is a child's marriage or another long-term milestone?
A long-term milestone may have more flexibility in its target amount than an education goal, even when the timeline remains important.
For parents specifically planning a future marriage corpus, How to Build a Marriage Corpus Through Goal-Based Investing for Parents explains how that individual goal can be structured.
If a goal of that kind is later projected to fall short, the framework on this page can be used to assess whether the contribution, additional investment, target or timeline needs to change.
How do you decide which part of an underfunded goal to change?
There is no single adjustment that works for every shortfall.
A higher monthly contribution may suit someone who has additional monthly surplus. A gradual step-up may be easier when income is expected to increase over time. An available lump sum can strengthen the goal without permanently increasing the monthly commitment, while more time may help when the deadline itself is flexible.
The target can also be reconsidered when the underlying expense can genuinely change.
What matters is comparing those alternatives against the same goal. If the target, timeline and return assumptions keep changing at the same time, it becomes difficult to understand whether the funding position has actually improved.
Review the goal after making the adjustment
Closing a projected gap once does not mean the goal will remain fully funded until the deadline.
Investment values change, contributions can be missed or increased, and the expected cost of the goal itself may change. The funding position should therefore be checked periodically and whenever there is a meaningful change to the plan.
How Do I Know If I’m On Track to Achieve My Financial Goal? explains how to assess that progress after the investment plan is underway.
If several goals are competing for the same monthly budget, return to I Have Multiple Financial Goals: How Should I Split My Monthly Investments? rather than treating every shortfall independently.
Frequently asked questions
What is a financial goal shortfall?
A financial goal shortfall is the difference between the amount you need on the goal date and the corpus your current investments and planned future contributions are projected to build by that date.
How do I calculate my financial goal shortfall?
Estimate the projected future value of the money already invested towards the goal and the contributions you expect to make until the deadline. Compare that projected corpus with your target amount. If the target is ₹50 lakh and the projected corpus is ₹44.3 lakh, the projected shortfall is approximately ₹5.7 lakh.
What should I do if my SIP is not enough for my financial goal?
Compare what happens if you increase the monthly SIP, introduce a calculated step-up, make an additional lump-sum investment, extend the deadline where possible or revise a genuinely flexible target. Keep the other assumptions consistent while comparing the alternatives.
Is increasing my SIP the only way to close a financial goal shortfall?
No. Depending on the goal, a shortfall may also be addressed through gradual contribution increases, additional lump-sum investments, more time or a revised target. The suitable adjustment depends on which parts of the goal are realistically flexible.
Can I increase the expected return instead of increasing my SIP?
A higher assumed return can improve a projection, but it does not increase the money being invested and the higher return may not occur. Changing an assumption should therefore not be used simply to make a funding gap disappear.
How often should I check whether my goal has a shortfall?
Review the funding position periodically and whenever the target amount, contribution, existing corpus or timeline changes materially. A shortfall identified earlier generally gives you more options than one discovered close to the goal date.
The calculations in this article are illustrative and are not a guarantee of future investment returns. Actual outcomes will depend on investment performance, contribution timing and changes to the goal.
Reviewed for financial accuracy by Ankita Shrivastava, Principal Officer, Nestvest.
Start Building Your Child's Future Today
Nestvest, powered by Wealthdoor Investment Advisers, gives your family a personalized, goal-based investment plan — no minimum, no jargon, fully regulated.