Actionable ideas for parents building long-term wealth and future-ready education plans.
Portfolio Structure
Goal-Based Investing •10 Sept 2026•4 min read
Do You Need a Separate Portfolio or SIP for Every Financial Goal?
Different financial goals should remain separately trackable, but that does not always mean using different mutual funds or SIPs. Learn when investments can overlap and how goal mapping keeps each target clear.
Author: Shweta Kataria (Content & Digital Marketing)
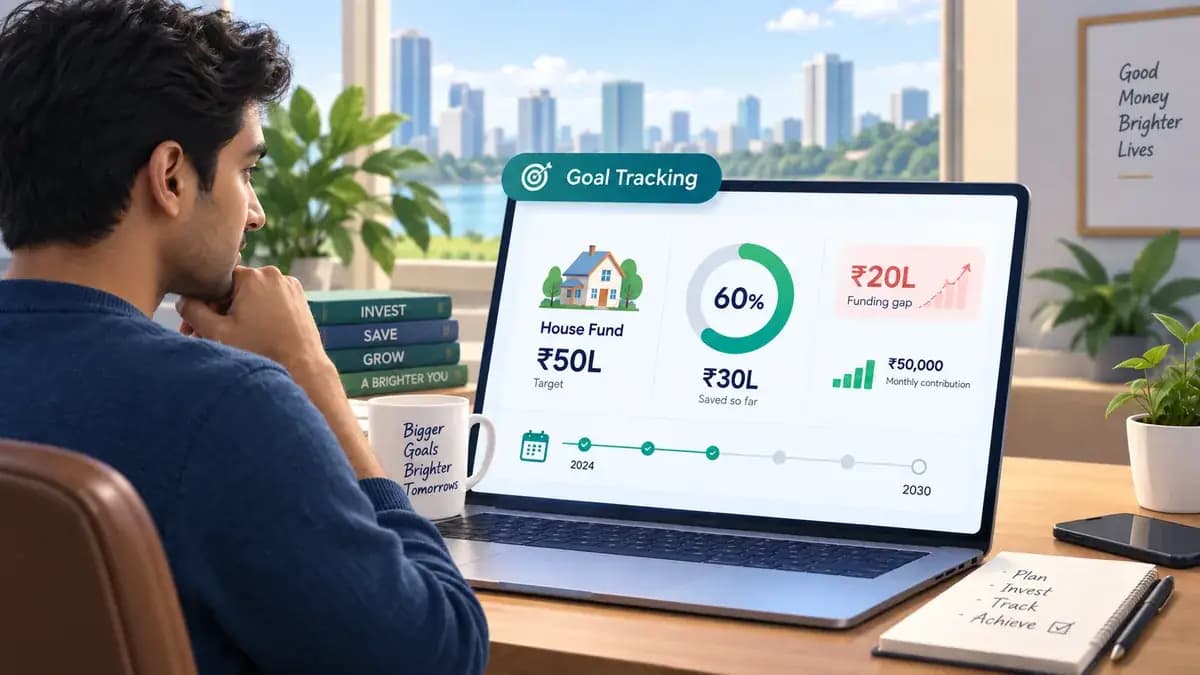
How Do I Know If I’m On Track to Achieve My Financial Goal?
Investment returns alone cannot tell you whether a financial goal is on track. Learn how to assess your current value, contributions, time remaining and funding gap against the amount you need.
Author: Shweta Kataria (Content & Digital Marketing)
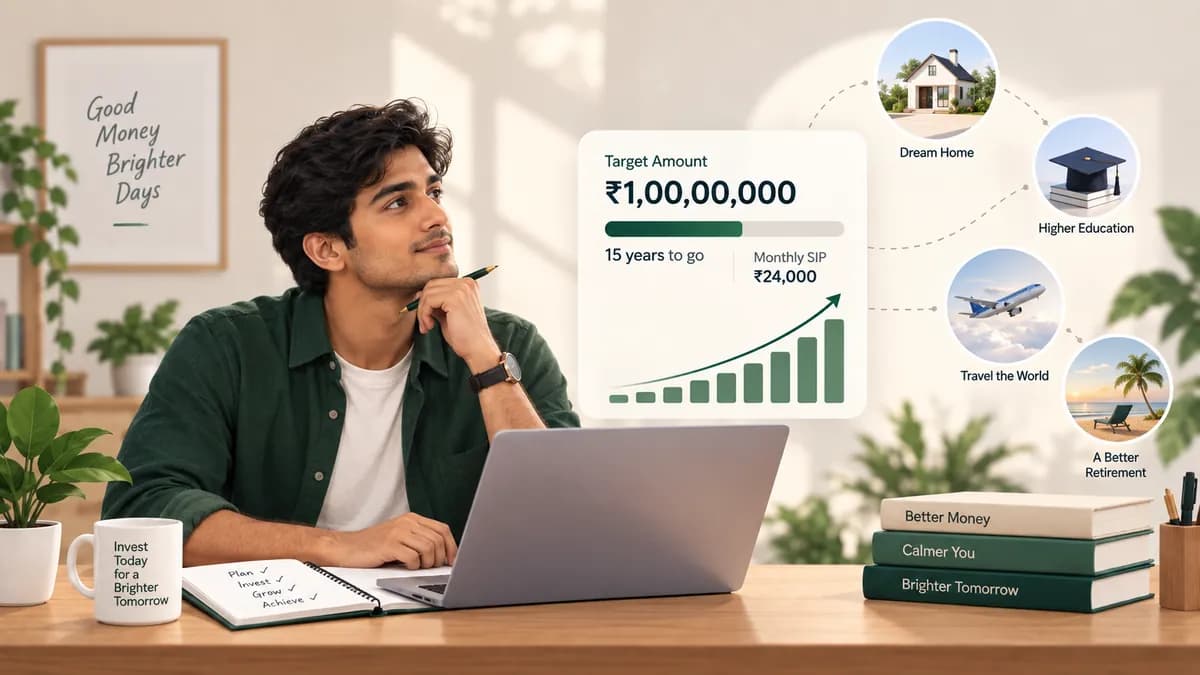
Goal-Based SIP: How Much Should You Invest Monthly to Achieve Your Financial Goal?
The SIP required for a financial goal depends on the target amount, time available, money already invested towards the goal and the return assumption used. See how the monthly requirement changes and what to do when it is more than you can afford.
Author: Shweta Kataria (Content & Digital Marketing)
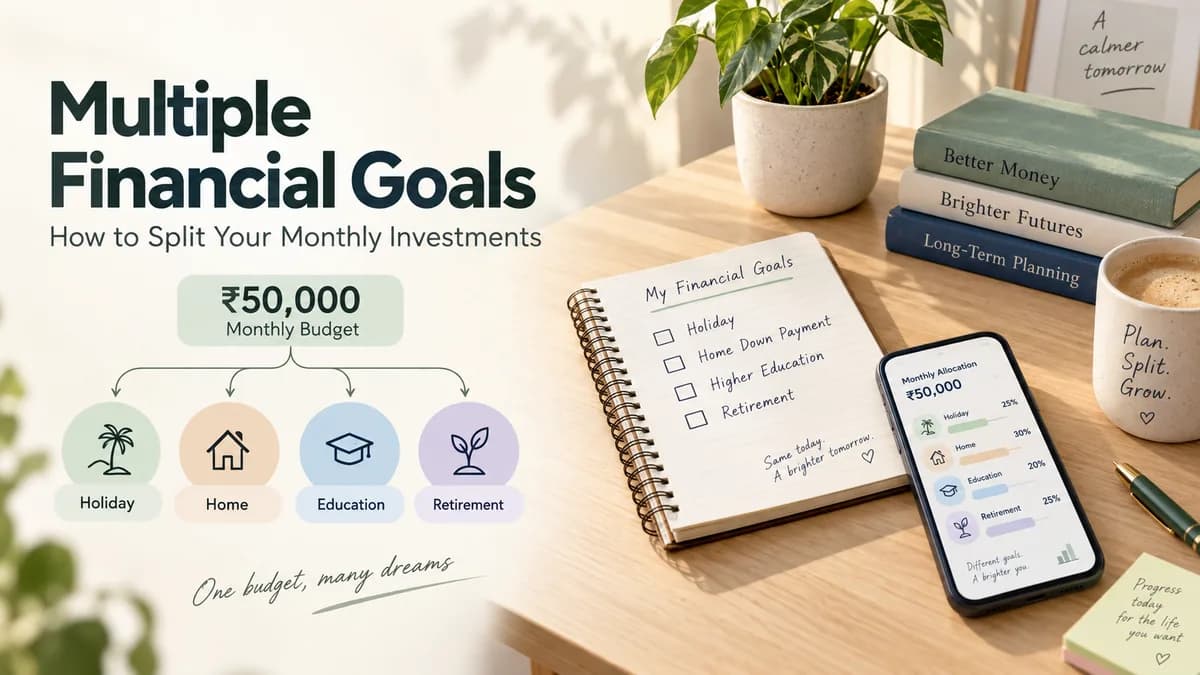
I Have Multiple Financial Goals: How Should I Split My Monthly Investments?
When several financial goals share one monthly investment budget, an equal split may not work. Learn how to compare what each goal needs, prioritize contributions and manage a funding shortfall.
Author: Shweta Kataria (Content & Digital Marketing)
How to Start Goal-Based Investing in India: A Step-by-Step Guide for Beginners
Turn a financial goal into an investment plan step by step. Define the target, set the timeline, estimate future cost, include existing savings and work out the monthly investment required.
Author: Shweta Kataria (Content & Digital Marketing)
What Is Goal-Based Investing? How It Works, Benefits & Examples in India
Goal-based investing starts with what you want your money to achieve. Learn how goals, target amounts, timelines and contributions come together to create a practical investment plan.
Author: Shweta Kataria (Content & Digital Marketing)
Bringing a baby home changes everything — including your finances. Learn how to plan for recurring newborn expenses, childcare, healthcare and future financial goals before your little one arrives.
What Expectant Parents Aren't Told: A Real Parenthood Guide
Social media shows the highlight reel. We show you the full picture — the emotional shifts, childcare realities, and financial changes every expectant parent needs to prepare for.
Beyond the College Fund: Mapping Your Child’s Dreams in 2026
In 2026, planning for your child’s future has evolved far beyond saving for a single university degree at age 18. Modern parenting is about funding the "new-age" milestones—from that magical first trip to Disneyland at age 6 to building a "Seed Capital" fund for their first startup.
The secret lies in categorizing investments into Short, Medium, and Long-Term buckets. Whether it is a Recurring Deposit for immediate travel or an aggressive Equity SIP for global exposure, your strategy must match the "Phase" of their journey.
Read the full guide to learn how to move past "survival saving" and start building a roadmap for their dreams, hobbies, and independence.
Before your child can invest in stocks, start a SIP, or build a financial future, they need one thing: a bank account in their own name. A minor's bank account is more than a place to store pocket money — it is your child's first financial identity, their first lesson in saving, and the foundation for every investment they will ever make. Here's why it matters, and exactly how to open one.
Raise a Saver: Fun Ways to Make Saving Money a Habit
Saving money is a habit — and like all habits, it's much easier to build when you start young. The good news? Teaching children to save doesn't have to feel like a chore. With the right approach, it can be genuinely exciting. Here are fun, practical ways to help your child fall in love with saving.
Minor Demat Account in India: How It Works, How to Open One & Its Benefits
Opening a demat account in your child's name might be one of the best financial decisions you ever make — not just for the returns, but for the mindset it builds. With a minor demat account, your child legally owns their investments from day one, and every rupee you invest has years — sometimes decades — to grow. Here's everything you need to know about how it works and how to open one.
Teaching Kids About Giving: The Power of Charitable Giving
Generosity is a vital part of financial education. Learn how to teach your child the value of charitable giving, build empathy, and raise a financially responsible child who understands money is a tool for good.
Bonds Explained: A Strategic Income Tool for Indian Investors
Over the last few years, many Indian investors—especially business owners and HNIs—have faced an uncomfortable reality.
Equity portfolios have delivered volatility without certainty, while traditional fixed deposits have struggled to beat inflation on a post-tax basis.
Author: Vijay Shelke (Head - Business Development)
Current Affairs/ Education•12 May 2026•10 min read
The World Is Uncertain — Your Investment Strategy Doesn't Have to Be
With global recessions, trade wars, rising interest rates, and geopolitical tensions reshaping economies, many investors are second-guessing their mutual fund SIPs. But is pulling out the smart move — or the costliest mistake you'll ever make? Discover why uncertain times may actually be the best time to invest in mutual funds, and how you can systematically build a generous financial corpus for your children even when the world feels unpredictable.
How to Teach Your Child the Difference Between Needs and Wants
One of the most foundational lessons in personal finance is knowing the difference between needs and wants. For children, this can be surprisingly tricky — a new toy can feel just as urgent as dinner! Teaching this concept early gives kids a framework they'll use for the rest of their lives. Here's how to make the lesson stick.
Pocket Money 101: Setting Up Your Child's First Budget
Handing your child their first few rupees is a proud parenting moment — but it's also a golden teaching opportunity. Pocket money isn't just spending money. When managed well, it becomes your child's first real experience with budgeting, saving, and making choices.
How to Choose a Financial Advisor in India (2026 Guide for Smart Investors)
Choosing a financial advisor is one of the most important decisions in your wealth creation journey. A wrong choice can lead to misaligned investments, high costs, and poor outcomes, while the right advisor can significantly improve long-term financial success.
This guide explains how to choose a financial advisor in India using a structured and practical approach.
Author: Vijay Shelke (Head - Business Development)
Goal-Based Planning vs Return-Chasing: Which Creates Real Wealth?
Every market cycle creates new “winning” assets, tempting investors to chase recent returns. But successful investing is less about predicting the next winner and more about building a disciplined strategy around financial goals. This article explores how goal-based investing compares with return-chasing and why the difference matters for long-term wealth creation.
Author: Vijay Shelke (Head - Business Development)
Children Financial Literacy•07 May 2026•5 min read
The Evolution of the Piggy Bank: Turning "Shagun" into a Financial Legacy
Receiving an envelope of Shagun is one of our most cherished traditions, but too often, these blessings end up forgotten in a drawer or spent on disposable toys. As a Principal Officer, I believe we owe our children more than just "safe keeping"—we owe them a strategic head start.
In this article, I share the "Untouchable Rule" I used for my own daughter: transitioning her savings from a simple piggy bank into a "Strategic Investment Universe" designed to fund her future dreams. Discover how to turn small, periodic windfalls into a powerful engine for wealth creation and beat education inflation before it even starts.
5 Best Investments for Kids in India: Build Their Financial Future Today
Did you know a SIP of just ₹5,000/month started at your child's birth can grow to over ₹2.7 crore by the time they turn 25? Time is the most powerful investment tool you have — and it starts ticking the moment your child is born. From the government-backed safety of PPF and Sukanya Samriddhi Yojana to the wealth-building potential of children's mutual funds, there are smart, accessible ways for every Indian parent to secure their child's financial future — starting with as little as ₹500 a month. Here are the 5 best investments for kids in India you need to know about
How Retail Investors Can Build a Down Payment Fund for Your First Home
Buying a first home is one of the biggest financial goals for many investors. Learn how goal-based investing can help you build a dedicated down-payment fund, choose investments based on your timeline and reduce the need for last-minute borrowing or forced withdrawals.
Author: Vijay Shelke (Head - Business Development)
Education Loan vs Investment: Why Indian Parents Should Avoid the Debt Trap
Education loans may fund degrees, but they can trap Indian families in years of high-interest EMIs. This article explains why early investing (SIP-based planning) is a smarter and more sustainable way to fund your child’s education goals.
The "Invisible" Portfolio: Why Your Child Needs Their Own Financial Identity
Most parents invest for their child — but not in their child's name. Tucking money into a personal portfolio folder labeled "Education" creates a financial fog that blurs your wealth from theirs, complicates taxes, and turns asset transfer into a nightmare. The fix is straightforward: a Minor PAN Card and a dedicated Minor Bank Account give your child a formal financial identity — clean, trackable, and fully theirs at 18. At Nestvest, we help you make that separation seamlessly, so your child's future is never just a sub-folder in your own life.
What Every Parent Must Do Financially After Childbirth
The birth of a child changes everything—emotionally and financially.
Yet, among high-income professionals and business owners, a recurring pattern emerges; portfolio decisions continue unchanged, while responsibilities quietly multiply.
Author: Vijay Shelke (Head - Business Development)
National Pension System (NPS) in India – Updated Rules, Types & Taxation
Over the past year, the National Pension System has undergone its most significant regulatory overhaul since inception.
With PFRDA’s December 2025 and January 2026 amendments, NPS now operates under a materially revised exit, withdrawal and continuation framework.
This document presents only updated NPS rules applicable in India as of May 2026, without interpretation, strategy or market positioning.
Author: Vijay Shelke (Head - Business Development)
The Parent’s Portfolio: Mastering Asset Allocation for Your Child’s Dreams
In 2026, being a young parent means managing a complex, 20-year financial project. While it is tempting to stick to "Safe FDs" or chase "Hot Stocks," true wealth for your child’s future is built through a precise "recipe" of Asset Allocation. From the Growth Engine of Equity to the Stabilizer of Debt and the Hedge of Gold, the magic lies in the proportions.
However, a "DIY" mix can be dangerous—too much debt slows growth, while too much equity invites risk. Discover how a SEBI Registered Investment Advisor (RIA) acts as your fiduciary partner, providing custom blueprints and objective advice to ensure you aren't just saving, but building a legacy that covers everything from a Disneyland trip to an Ivy League degree.
The Great Debate: Sukanya Samriddhi Yojana (SSY) vs. Equity SIP
Parents of girl children in 2026 face a crucial financial decision: should they rely on the guaranteed safety of Sukanya Samriddhi Yojana (SSY) or aim for higher wealth creation through Equity Mutual Fund SIPs? While SSY offers tax-free, government-backed stability at 8.2%, equity SIPs provide the potential for inflation-beating long-term growth. The real answer, however, may not lie in choosing one over the other. This blog explores how combining SSY for security and SIPs for growth can create a balanced strategy to fund your daughter’s education, marriage, and future aspirations with confidence.
The Great Gold Pivot: Why India's Smartest Parents Are Ditching the Locker
For generations, gold in India was an emotion — the wedding jewellery, the locker heirloom, the silent emergency fund. But in 2026, something has shifted.
The modern Indian investor is no longer content letting gold collect dust. Between the hidden wealth leaks of making charges, storage costs, and purity uncertainty, physical gold has quietly been one of India's most expensive traditions.
Today, savvy parents are treating gold like a portfolio asset — earning 2.5% annual interest through Sovereign Gold Bonds, running weekly "Gold SIPs" from as little as ₹100, and rebalancing in seconds from their phone. No emotional negotiations with a jeweller. No locker fees. No tax surprises.
The question is no longer how much gold do you own — it's is your gold actually working for you?
Tight enough for a blog intro or social caption, and ends on the hook that drives readers into the full piece.
Planning for a Disney trip is about more than just flight alerts; it’s about "Goal-Based Planning." By mapping out the "Invisible Costs" of magic and automating our savings into dedicated funds, we proved that a luxury vacation can coexist with long-term financial security. Learn how visualizing your child’s timeline—from their first steps to their university graduation—provides the confidence to enjoy the magic today.
How to Build a Marriage Corpus Through Goal-Based Investing for Parents
A child’s marriage can be one of a family’s largest future expenses. Learn how goal-based investing can help parents estimate the future corpus, account for inflation, select investments according to the timeline and build toward the goal systematically.
Author: Vijay Shelke (Head - Business Development)
Children Financial Awareness•15 Apr 2026•7 min read
Child Education Planning in India: A Complete Beginner Guide for Parents
Most Indian parents don’t underestimate their love for their child’s education.
They underestimate the cost of it.
A professional degree that costs ₹15–20 lakh today can easily demand ₹50–70 lakh by the time a child reaches college. Parents often realise this too late—when choices narrow, loans increase, and retirement savings get compromised.
Child education planning is not about picking a product early.
It is about structuring capital deliberately, keeping inflation, taxation, and risk in mind—well before the pressure years arrive.
Author: Vijay Shelke (Head - Business Development)
Fixed Deposits vs Debt Mutual Funds: A Strategic Choice for Indian Investors in a Changing Rate Cycle
For decades, Indian investors have treated Fixed Deposits (FDs) as the default destination for surplus capital. The logic was simple—capital safety, predictable income, and institutional trust.
Yet over the last few years, many investors—especially business owners and high‑income professionals—have faced an uncomfortable reality:
their “safe” money is quietly losing purchasing power.
Rising inflation, frequent changes in interest rates, and evolving tax laws have made the traditional FD‑heavy approach increasingly inefficient for long‑term wealth preservation.
Author: Vijay Shelke (Head - Business Development)
Investment Risks Explained: The Reality Beyond Textbooks
If you observe markets for over two decades, one truth becomes undeniable risk is not what textbooks define, it’s what investors actually experience.
Most financial blogs reduce risk to volatility. But risk is multi-dimensional, behavioural, and deeply personal.
This is not a theoretical breakdown. This is how risk unfolds in real portfolios, real clients, and real wealth journeys.
Author: Vijay Shelke (Head - Business Development)
In a market flooded with wealth advisers, retirement planners, and trading apps, one question keeps getting ignored: who is actually planning for your child's future?
Not as a line item. Not as a footnote in your portfolio review. But as the single most important financial goal of your life.
Most advisers aren't built for this. They miss the compounding urgency of education inflation, the unique 15-year wealth-building window, and the emotional weight behind every rupee a parent sets aside.
Nestvest was built to fill exactly that gap — as India's only SEBI Registered Investment Adviser laser-focused on children's wealth management. From seamless onboarding to AI-driven goal portfolios, every feature is engineered around one question: what does your child's dream actually need to become real?
Your child's future isn't a sub-goal. It's the only goal that matters.
ETFs in India: A Smart Portfolio Building Tool for Long-Term Investors
Over the last decade, Indian investors have become far more cost-conscious and risk aware. Traditional active funds still dominate portfolios, but rising market volatility, inconsistent alpha, and higher expense ratios are forcing serious investors to rethink their allocation strategy.
For business owners and high-net-worth investors, the question is no longer whether to diversify—but how efficiently it can be done without compromising governance, transparency, or long-term outcomes. This is where ETFs in India are increasingly finding a place in well-constructed portfolios.
Author: Vijay Shelke (Head - Business Development)
Certificate of Deposits (CDs): Meaning, Types, Benefits and Limitations for Investors
In periods of economic uncertainty, volatile equity markets, and shifting interest rate cycles, investors often seek instruments that prioritise capital preservation and predictability over aggressive growth. Across global banking systems, Certificate of Deposits (CDs) have historically served this role—offering structured, time-bound returns with clearly defined risks.
Author: Vijay Shelke (Head - Business Development)
Children Financial Awareness•27 Mar 2026•5 min read
Biggest Mistakes Parents Make While Investing for Children
When Good Intentions Lead to Poor Outcomes
Most parents invest for their children with the right intent—education security, global exposure, or financial independence. Yet many portfolios fail to meet the goal when it actually arrives.
Not because parents didn’t save enough—but because structural and behavioural mistakes were made early.
Author: Vijay Shelke (Head - Business Development)
Financial Planning vs Goal-Based Planning: What Should You Follow?
Financial planning creates the foundation for managing your money, while goal-based investing connects your investments to specific outcomes and timelines. Understand how the two approaches differ, where each fits and how they can work together to build a more purposeful investment plan.
Author: Vijay Shelke (Head - Business Development)