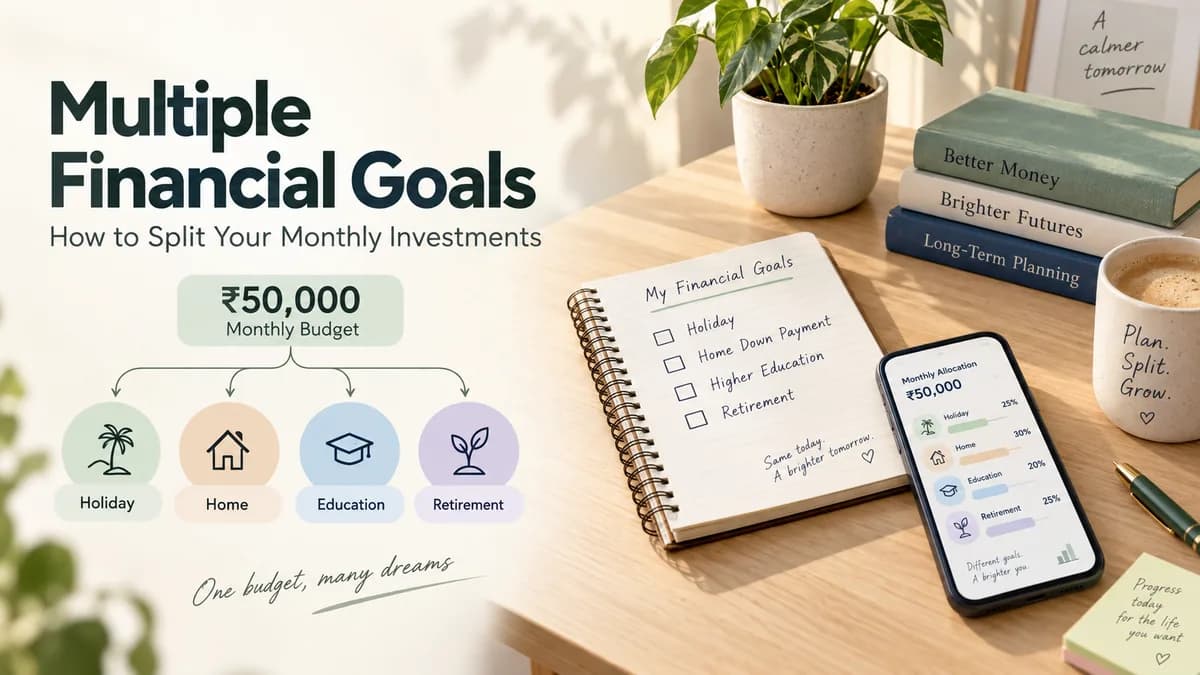
I Have Multiple Financial Goals: How Should I Split My Monthly Investments?
When several financial goals share one monthly investment budget, an equal split may not work. Learn how to compare what each goal needs, prioritize contributions and manage a funding shortfall.
07 Sept 2026 • 5 min read • Shweta Kataria (Content & Digital Marketing)
How Should I Split My Monthly Investments?
When you have several financial goals, do not automatically divide your monthly investment equally between them. First calculate how much each goal requires based on its target amount, timeline and existing savings. If the combined requirement is more than you can currently invest, compare which goals have less flexible deadlines and which goals can be delayed, reduced or funded more gradually.
The aim is not to create an equal split. It is to give each goal a contribution that reflects what that goal actually needs.
Most people are saving for more than one thing at a time.
You may be planning for a holiday next year, a house down payment in six years, higher education later on and retirement much further away.
The question is how much of your monthly investment should go towards each one.
Dividing the money equally may seem like the simplest approach, but your goals are unlikely to need the same amount. They may have different costs, timelines and amounts already saved.
Before deciding on the split, work out what each goal needs.
If you have not done that yet, start with How to Start Goal-Based Investing in India: A Step-by-Step Guide for Beginners.
Work out what each goal needs first
Put the goals side by side before deciding where the monthly money should go.
Goal | When is the money needed? | Already saved | Monthly amount needed | How flexible is the date? |
Holiday | 1 year | Add existing savings | Calculate for this goal | Usually flexible |
House down payment | 6 years | Add existing savings | Calculate for this goal | Depends on your plans |
Higher education | 15 years | Add existing savings | Calculate for this goal | Often less flexible |
Retirement | 25 years | Add existing investments | Calculate for this goal | Long timeline |
If you have not yet calculated the monthly amount required for an individual goal, Goal-Based SIP: How Much Should You Invest Monthly to Achieve Your Financial Goal? covers that calculation separately.
When your goals need more than your budget allows
Once you know what each goal requires each month, add the amounts together and compare the total with what you can invest.
Suppose your goals together require ₹75,000 a month, but your current investment budget is ₹50,000.
That leaves a ₹25,000 shortfall.
Example: How could ₹50,000 be split across several goals?
Suppose four goals together require ₹75,000 a month:
Goal | Monthly amount calculated | Flexibility |
|---|---|---|
Holiday | ₹10,000 | High |
House down payment | ₹20,000 | Some flexibility |
Higher education | ₹25,000 | Lower flexibility |
Retirement | ₹20,000 | Long timeline |
Total required | ₹75,000 |
If only ₹50,000 is currently available, simply putting ₹12,500 into each goal would ignore the fact that the goals have different requirements.
Instead, the investor could review the goals individually. For example, a holiday may be postponed or its budget reduced, while a goal with a less flexible deadline may continue to receive a larger share of the available investment. A long-term goal may also have more time for future increases in contributions.
There is no universal ₹50,000 split that works for everyone. The appropriate allocation depends on the target amount, time remaining, money already saved and how much flexibility each goal allows.
Dividing the available amount equally does not solve the shortfall. Some goals will still receive less than they need.
For a goal planned through Nestvest, you can see the probability of reaching the target based on the amount you are currently investing.
If the contribution is lower than required, you can keep the original target and strengthen the plan later through annual step-ups, top-ups or additional contributions.
You can also revise the goal amount if a lower target is more realistic with the money currently available.
For goals where there is some flexibility, the date or target may also be reconsidered.
How Do I Prioritize Multiple Financial Goals?
There is no fixed order that works for everyone.
A shorter deadline does not always mean the goal should get the most money, and the largest goal does not always need to come first.
The decision depends on the full picture: how soon the money is needed, how much is already available and how much room there is to change the target or date.
For example, if higher education is due in three years and the target is still well short, it may need more attention than a goal that is 15 years away.
A flexible goal can sometimes take a smaller contribution for a while and be increased later.
What if one goal is still underfunded?
If a goal needs ₹25,000 a month and you can currently put in ₹17,000, there is an ₹8,000 gap.
You may be able to close part of that gap through an annual step-up in the monthly contribution, an ad hoc top-up when extra funds are available, or a larger contribution from a bonus or other lump sum. If the date is flexible, postponing the goal or revising the target may also be considered.
A combination may work better for a long-term goal. You can invest what is affordable today and increase the contribution as your income and available funds change.
If you want to assess one underfunded goal in detail, Financial Goal Shortfall: What to Do When Your SIP Is Not Enough compares the effect of a higher SIP, additional investment, timeline change and revised target.
Your split can change over time
The amount going towards each goal does not need to stay the same for years.
Your income may rise. A goal may be completed. You may receive a bonus. The expected cost of another goal may change.
If a holiday is fully funded next year, the money that was going towards it can then be redirected to another goal.
Review the split when something important changes rather than treating the first allocation as permanent.
How Nestvest approaches multiple financial goals
Parents may be preparing for several expenses in their child’s future at the same time.
Higher education may be the largest goal, but there may also be a school trip, laptop, sports programme, course or another milestone much earlier.
Nestvest allows parents to plan these goals separately, so each can have its own amount and timeline.
A goal can then be planned using factors such as its expected future cost, the time available, money already saved and the parent’s risk profile.
Parents can invest towards those goals and track their progress over time. How Nestvest Works
Frequently asked questions
Can I invest for several financial goals at the same time?
Yes. Work out how much each goal may need and when the money will be required, then compare the combined monthly amount with what you can invest.
Should I divide my monthly investment equally between all my goals?
Usually not. Goals can have different costs, deadlines and existing savings, so equal contributions may not suit what each one needs.
How should I split ₹50,000 a month between my financial goals?
There is no standard split. Calculate the monthly requirement for each goal first, then use the deadlines, existing savings and flexibility of the goals if the total is more than ₹50,000.
What if I cannot afford all my financial goals?
You may need to increase contributions later, use lump sums, move a flexible deadline or revise the target for some goals.
Can I change the split later?
Yes. The allocation can change as your income, goals and savings change. Money freed up after one goal is completed can also be moved to another.
Reviewed for financial accuracy by Ankita Shrivastava, Principal Officer, Nestvest.
Start Building Your Child's Future Today
Nestvest, powered by Wealthdoor Investment Advisers, gives your family a personalized, goal-based investment plan — no minimum, no jargon, fully regulated.